Who Gets the $30 Trillion?
We have written quite a bit about artificial intelligence, mostly because we believe the excitement surrounding it is justified. We are talking about how we all work will change, not necessarily the valuations being placed on the companies developing it. The capabilities continue to improve at a pace that surprises us, and it is becoming easier to imagine AI having a meaningful impact on productivity and the broader economy. But every once in a while, a number comes along that makes us stop.
Anthropic (the company behind Claude AI) has reportedly discussed a potential market of more than $30 trillion. SpaceX, in its filing to go public, estimates its total potential market at $28.5 trillion, with roughly $26.5 trillion of that coming from AI.
Those numbers sound enormous, don’t they? For perspective, the entire world produces around $120 trillion of goods and services each year. Worldwide spending on information technology is around $6 trillion annually. Yet we now have individual companies looking at potential markets approaching $30 trillion.
At first, the numbers seem almost silly. But digging into them reveals something more interesting. These companies aren't really measuring the market for technology as we have traditionally thought about it. They are increasingly measuring the value of work people currently do. And the management teams at these companies wonder why there is backlash against AI from so many people…
Think about an employee who costs a company $150,000 a year. Historically, the company might spend a few thousand dollars providing that employee with software and other technology. If AI simply becomes another tool that makes the employee more productive, then AI competes for a piece of that technology budget.
But if AI can replace some or all of the work that employee performs, the potential market is no longer a few thousand dollars spent on software. It becomes some portion of the $150,000 spent on the employee. Do that across programmers, accountants, attorneys, customer-service representatives, analysts, and countless other occupations, and suddenly it becomes possible to understand how someone arrives at a number measured in tens of trillions.
However, that math rests on a pretty important assumption. To turn the value of the work being performed into the AI company's addressable market, the AI provider needs to capture a meaningful portion of the savings. We are not sure whether management teams truly believe they will capture most of those economics or whether enormous addressable markets are simply helpful in supporting enormous valuations. Either way, a big gap exists between the value of the work AI might perform and the revenue ultimately collected by the companies providing it.
We don't know whether $30 trillion is the right number. Given how quickly the technology is developing, we aren't particularly interested in arguing that it is too high. The more interesting question is what happens to that $30 trillion if AI really does become capable of performing that much work. Let’s break this down into a few examples.
Suppose AI can perform $100 worth of work that previously required a person. Does the company providing the AI get paid $100? Maybe, but probably not. Perhaps it gets $50, and the company using the AI keeps the other $50 through higher profits. That would still create an extraordinary business for the AI provider and a pretty compelling reason for the customer to adopt it.
But now assume another AI company can perform the same work and charges $30. Another offers to do it for $20. If the underlying cost of providing AI continues to decline, the price could fall further still. The original $100 of work hasn't disappeared, and the benefit of AI hasn't become any less impressive. What has changed is how that $100 gets divided. Instead of the AI company collecting most of it, the business using AI may keep much more of the savings.
There is another step. If two competing businesses can both use AI to lower their costs, they may eventually compete some of those savings away. Prices fall, customers benefit, and the economic value created by AI spreads even further. The $100 of work may still be getting done, perhaps better and faster than before, but the AI provider might ultimately collect only $10 or $20 for making it possible. In every one of these examples, AI worked. What changed was who received the benefit.
This brings us back to something we wrote about recently in When Monopolies Go to War. For years, many of the largest technology companies occupied wonderfully profitable corners of the technology world. Google had search. Microsoft had enterprise software. Amazon had e-commerce and cloud computing. Meta had social media. Apple had its devices and ecosystem. We argued in that piece that AI has brought them all into the same field.
They are now spending extraordinary amounts of money pursuing many of the same customers and capabilities. Add OpenAI, Anthropic, xAI, and others to the mix, and we have some of the best-funded and most capable companies in the world competing for the same opportunity. Importantly, they are doing so while taking on enormous fixed expenses for data centers, chips, power, and talent. That is quite different from defending an already established ecosystem where the incremental cost of adding another customer could be relatively small.
This matters when considering who gets the $30 trillion. If one company can provide $100 worth of work for $20, there is a powerful incentive for someone else to offer it for $15. These companies are not only competing to build the most capable AI; they are competing over price, distribution, and customers while spending enormous sums to remain in the race. If the cost of providing AI continues to fall, as it has been, some of the economics they are currently including in their addressable markets may ultimately accrue to everyone except the AI provider.
This is where the $30 trillion numbers become particularly interesting. Anthropic can identify a potential market of more than $30 trillion. SpaceX can identify nearly $30 trillion of its own. Other companies can look at the same economy and identify enormous opportunities as well. They haven't each discovered a different $30 trillion. They are looking at many of the same dollars.
None of this dampens our enthusiasm for AI. If anything, the fact that we can reasonably discuss a technology affecting tens of trillions of dollars of economic activity reinforces how consequential it may become. But there is an important distinction between changing $30 trillion of economic activity and collecting $30 trillion from it.
Perhaps a simpler way to think about this is to imagine a company that develops a remarkable new lubricant for a wheel. The lubricant allows the wheel to turn faster, last longer, and operate with less friction. Its value could be substantial, and the manufacturer should certainly be paid for that improvement. But it would be a stretch for the lubricant manufacturer to look at everything made possible by the wheel and claim that entire economic value as its potential market. Some of that value belongs to the lubricant, some to the wheel, some to the machine it powers, and much of it ultimately belongs to whoever finds a productive use for the machine. AI may prove vastly more important than our imaginary lubricant, but the economic question is similar. Enabling more economic activity does not necessarily mean capturing the value of all the activity you enable.
History has repeatedly shown that great technologies can create enormous value while spreading much of that value beyond the companies that invented them. Employees become more productive. Businesses pay their workers more for that productivity. New businesses emerge. Competition pushes prices down. Consumers benefit. AI may prove to be one of the greatest examples yet.
For investors, recognizing that AI could change the world may be the easy part. Figuring out who gets the $30 trillion will be considerably harder.
A Walk Down Memory Lane
In the late 1990s, telecommunications companies spent extraordinary amounts of money building the infrastructure needed for an expected explosion in internet traffic. One popular claim at the time was that internet traffic was doubling every 100 days. That proved far too aggressive, but the direction was certainly right. Internet traffic did grow extraordinarily quickly and ultimately became vastly larger than anyone could have imagined at the time.
That didn't work out particularly well for many of the companies that built the infrastructure.
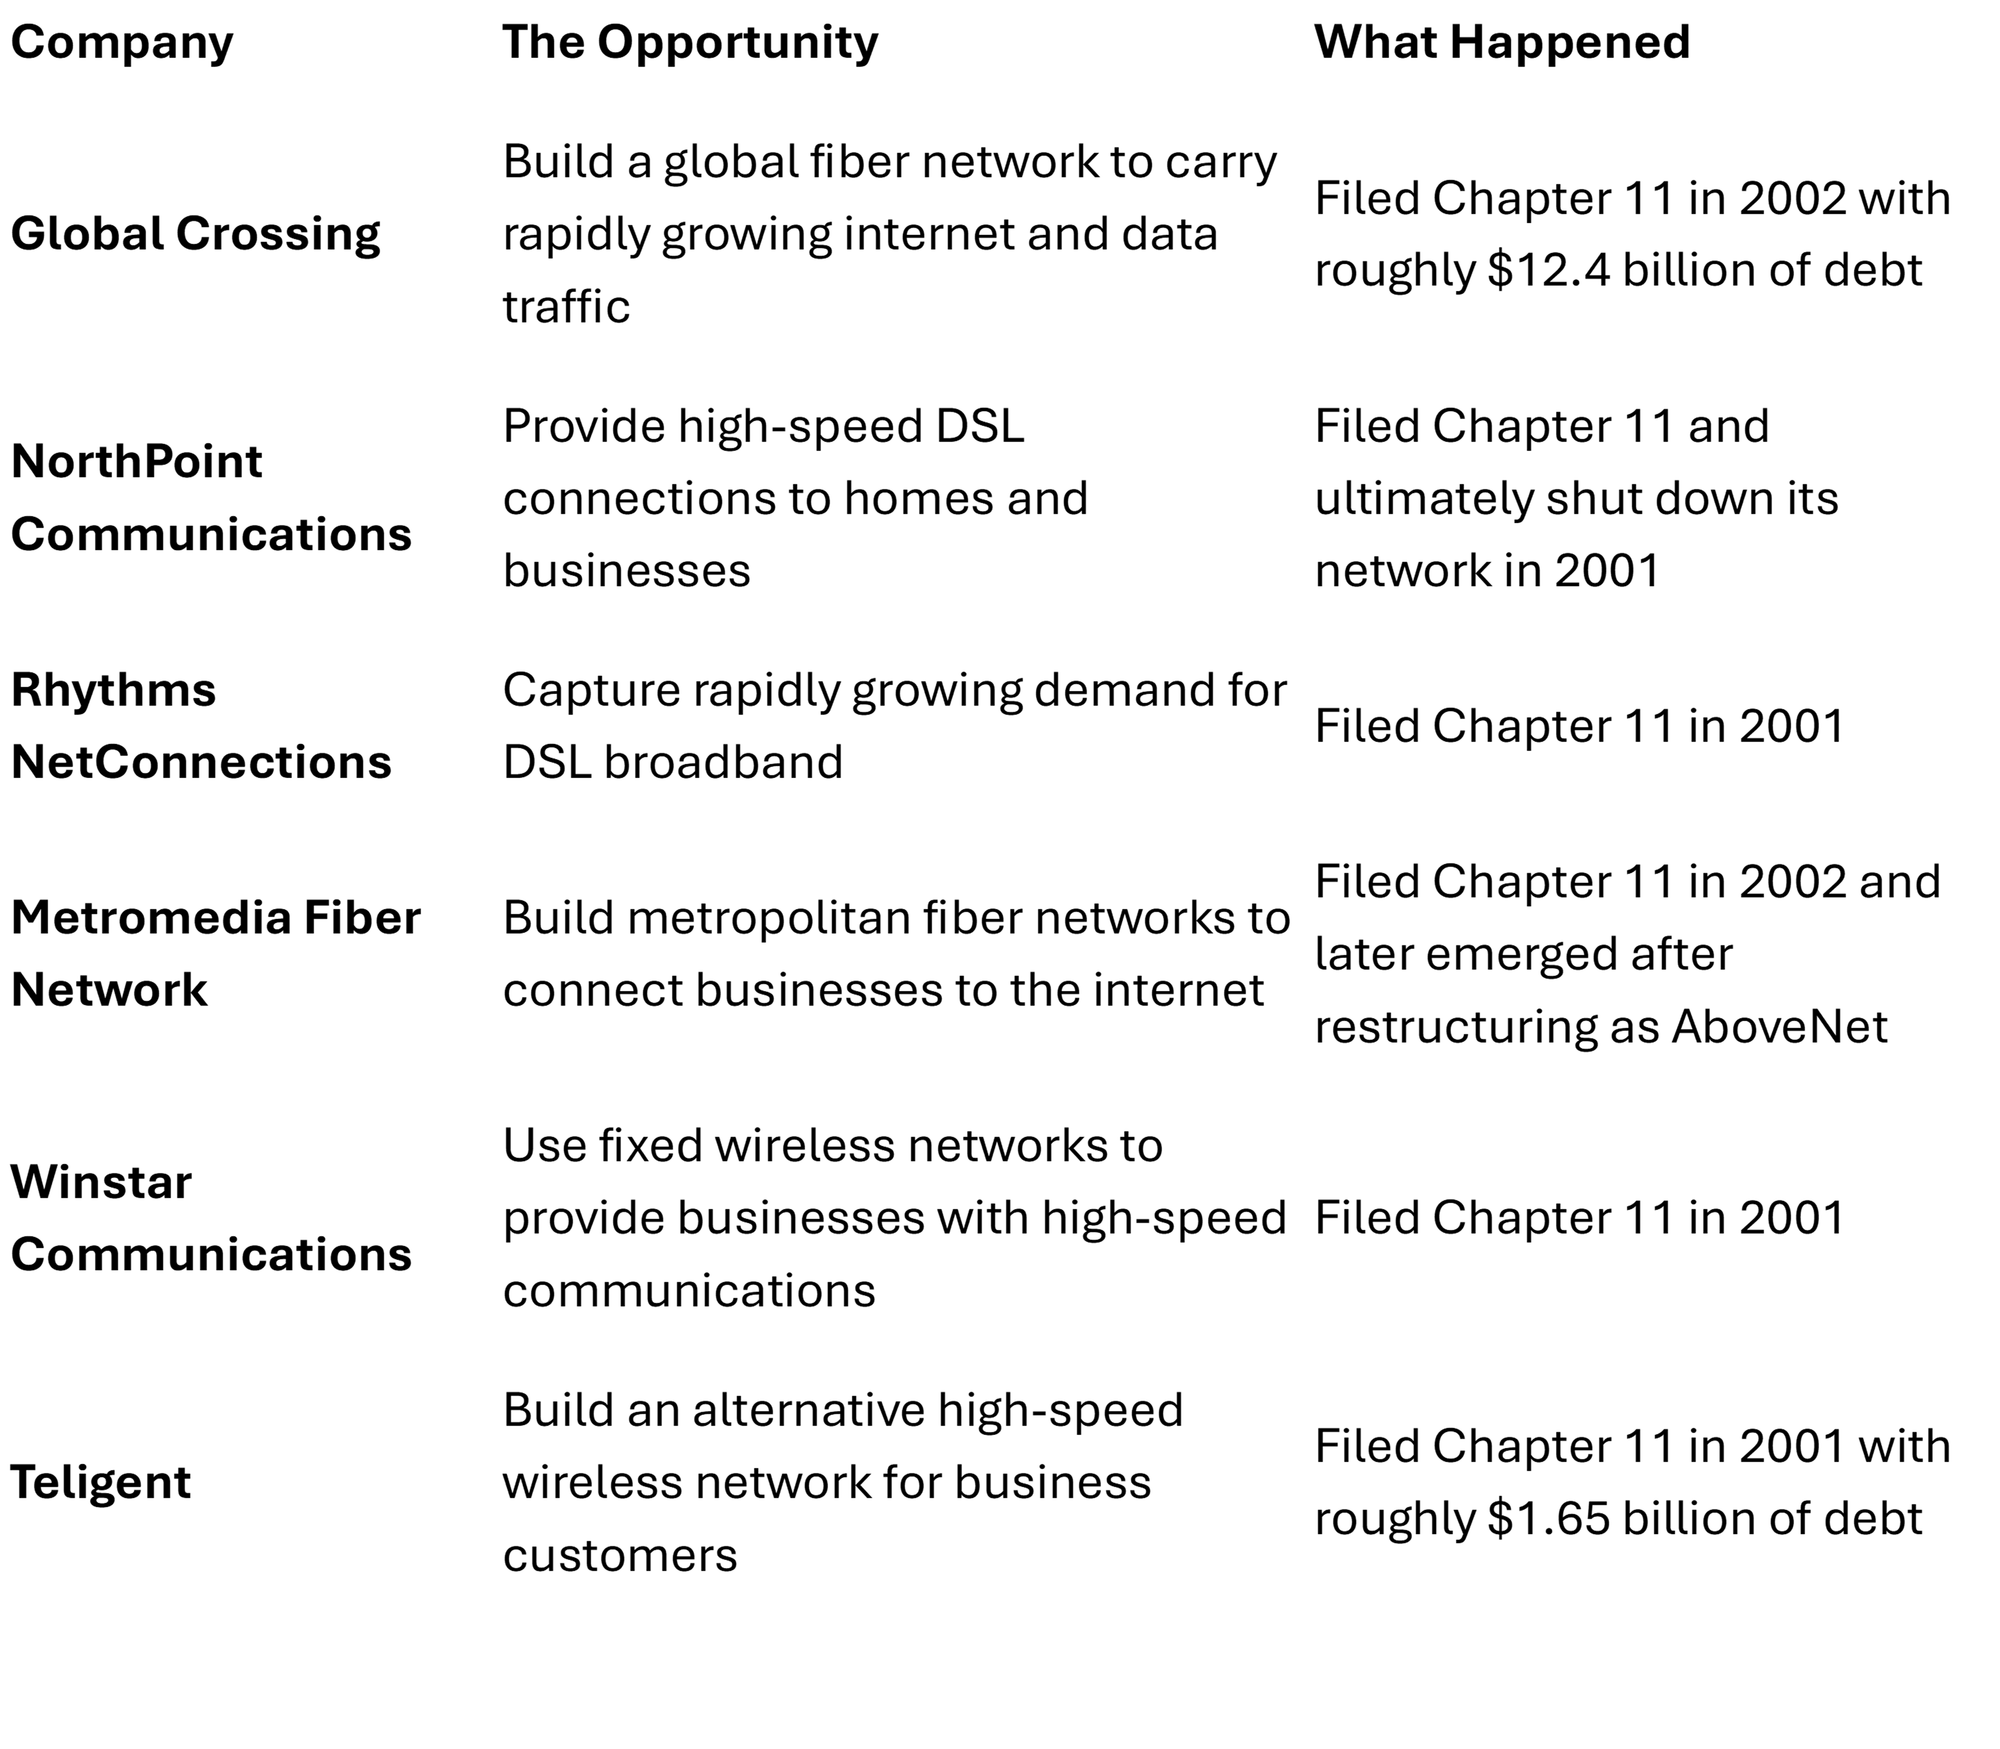
By one estimate, the telecom collapse ultimately erased roughly $2 trillion of shareholder value.
What makes the episode relevant today is that the fundamental prediction wasn't necessarily wrong. We really did end up consuming extraordinary amounts of data. Broadband became ubiquitous, businesses moved online, smartphones put an internet connection in nearly everyone's pocket, streaming replaced much of traditional television, and cloud computing created an entirely new technology infrastructure.
The problem was that enormous growth in the amount of data being carried did not mean that the companies carrying it would capture an equally enormous amount of economic value.
Everyone was building at the same time. Technology allowed existing fiber to carry increasingly more information. Capacity became abundant, and bandwidth prices fell. Companies that had spent and borrowed heavily based on the assumption that rapidly growing demand would make their networks increasingly valuable discovered that demand could explode at the same time the price of what they were selling collapsed.
The internet was enormously successful. Many of the companies building its highways were not.
We don't know whether artificial intelligence will follow anything resembling that path, and there are plenty of reasons why it may not. But the experience is a useful reminder of the distinction we are trying to make. The companies spending hundreds of billions of dollars on AI today may be absolutely correct about how much intelligence the world will eventually consume. They may even be underestimating it.
Being right about how much we use is not necessarily the same as being right about what we will pay for it.
Important Disclosure: This material is provided by Auour Investments, LLC (“Auour”), an SEC-registered investment adviser, for informational and educational purposes only and should not be considered investment advice or a recommendation to buy or sell any security. References to specific companies, securities, technologies, industries, or historical events are for illustrative purposes only and should not be interpreted as an endorsement or investment recommendation. The views expressed reflect Auour’s opinions as of the date of publication and are subject to change without notice. Certain information, estimates, market data, and statements regarding future expectations have been obtained from sources believed to be reliable; however, Auour does not guarantee their accuracy or completeness. Forward-looking statements and estimates are inherently uncertain, and actual results may differ materially from those discussed. Historical examples are provided for context and do not imply that current or future market conditions will produce similar outcomes. Investing involves risk, including the possible loss of principal. Past performance is not indicative of future results.